BUSINESS
IMF Warns Circular AI Deals Can Unwind the Growth They Fund
The IMF lifted 2026 growth to 3.1% on AI spending, then warned $1.4tn in circular deals could turn a miss into a global market shock.

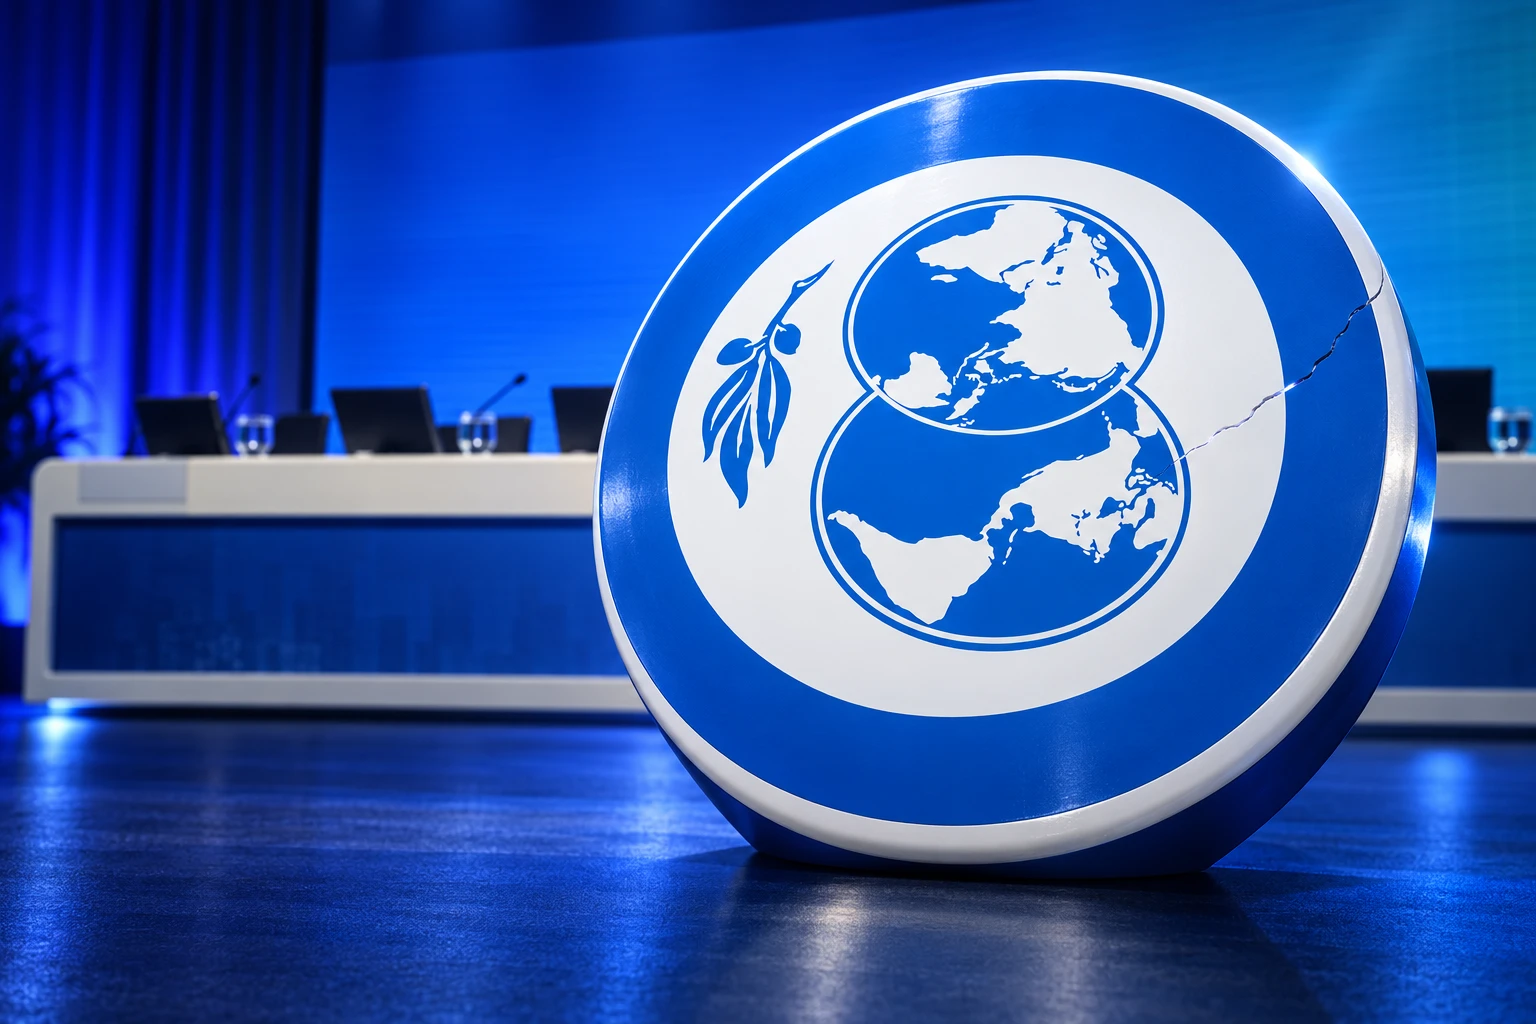
The IMF said on October 13 that $1.4 trillion in circular AI deals could deepen a market correction if investment and profits disappoint. It named that risk as one of three shocks that could tighten financial conditions worldwide, alongside a jump in government bond yields and a major cyber incident.
The same day, in the same Bangkok meetings, the Fund raised its 2026 global growth forecast to 3.1%, from 3 percent in July, on the back of that AI spending.
14 Deals Put $1.4 Trillion of Orders on Weaker Firms
The three risks that could tighten financial conditions sit in the October Global Financial Stability Report, titled Resilience, Risk, and Transformation. Weaker or less durable AI investment and profits could trigger a correction in related stocks and debt, the Fund said, and rising borrowing, concentrated bets, and circular financing could make the break worse.
Staff reviewed 14 publicly disclosed deals struck since 2023. Investors led by hyperscalers, the large cloud and data-centre operators, put about $300 billion of equity into financially weaker AI firms and lined up $650 billion of debt. In return they locked in $1.4 trillion of future revenue through services or chip orders. About $320 billion of the debt sits with the firms that received the money, and a handful of those firms hold most of the financing and the promises.
THE MONEY INSIDE 14 PUBLIC AI DEALS
| Piece of the loop | Amount | Where it sits |
|---|---|---|
| Equity into weaker AI firms | about $300 billion | Hyperscalers and other investors |
| Debt, including off-balance-sheet vehicles | $650 billion | Split across borrowers and funding vehicles |
| Debt on recipient books | about $320 billion | The weaker AI firms themselves |
| Future chip and cloud orders | $1.4 trillion | Revenue promised back to the investors |
Each dollar of equity in that sample is paired with more than two dollars of debt and more than four dollars of promised future sales. If the sales do not arrive, the stake, the loan, and the order book can all weaken together. The Fund’s name for that overlap is wrong-way risk: “Equity and debt investments in the firms depreciate in value precisely when future revenue streams tied to them are impaired.”
The pattern is already visible in public contracts. Chipmakers take equity in neocloud operators that buy their processors. Cloud groups put capital into model labs that then sign long compute and chip orders. The labs, the lessors, and the suppliers end up as one another’s investors, lenders, and customers at once.
Global financial markets face growing risks from AI, bond yields, and cyberattacks. As vulnerabilities increase, policymakers should contain leverage, strengthen debt sustainability, and harden cyber defenses.
Read our new blog: https://t.co/jJzedXypzs pic.twitter.com/Gi6A4aq7nz— IMF (@IMFNews) October 13, 2026
The Same Spending Lifted the Global Growth Forecast
Managing Director Kristalina Georgieva had already set the growth story on October 12, the opening day of the IMF-World Bank annual meetings. She told the hall that AI investment was delivering a demand shock and an investment shock, and that this was what held global growth near 3 percent even as an energy supply shock pulled the other way.
That shift into higher gear is what is keeping the world economy growing at around 3%, despite the fact we are being dragged down by the energy supply shock.
Kristalina Georgieva, IMF managing director, remarks in Bangkok
The World Economic Outlook published the next morning put a finer point on it. Global growth is projected at 3.1 percent in 2026, a 0.1 percentage point upgrade from July, then 3.4 percent in 2027. That is still a slowdown from 3.5 percent in 2025. The Fund said the technology upturn, buffers, and private-sector adaptation had so far limited the damage from geopolitics, and it listed a reassessment of AI expectations among the downside risks that could weaken growth.
THE BANGKOK CALENDAR
- October 9, 2026: Yingyuan Chen, Deepali Gautam, and Jason J. Wu publish a staff technical note mapping circular financing across the AI value stack.
- October 12, 2026: Georgieva says AI investment is keeping global growth around 3 percent and that advanced Asian economies could gain 0.5 to 1 percentage point from the hardware boom, with emerging Asia at 0.2 to 0.8.
- October 13, 2026: The Fund releases the stability report and the World Economic Outlook together in Bangkok.
Hardware exporters are on both sides of that ledger. The growth paper credits them for part of the upgrade. Jason Wu, an assistant director in the Monetary and Capital Markets Department, told reporters that Thailand’s AI hardware shipments had helped offset higher energy prices, and that a correction in AI markets could hit those exports and weigh on currencies in emerging economies.
The Fund also noted growing evidence that AI systems may not need as much capital as the current build-out assumes, or that the economic gains may be smaller than investors have priced. That is the trigger the stability report is built around: a break in the spending that the growth report still needs.
Hyperscalers Now Issue 10% of Investment-Grade Bonds
The circular deals sit on a funding shift that is already large enough to show up in the global credit market. Hyperscalers now issue 10% of the world’s investment-grade bonds, the stability report said. In 2024 that share was less than 1 percent. Their free cash flow is falling fast as they keep spending on AI, so debt is doing more of the work.
Capital Group, looking at a narrower set of names, counted $240.7 billion of hyperscaler bonds this year through August 31 from Alphabet, Amazon, Meta, Microsoft, and Oracle, including $66 billion in non-dollar currencies. That dollar total and the IMF’s 10 percent share are different gauges: one is year-to-date issuance by five firms, the other is those firms’ weight in world investment-grade supply. Both point the same way. Companies that once funded expansion from cash are now standing in the same bond queue as governments.
Neocloud operators, which rent GPU capacity rather than run a full public cloud, carry more debt and thinner profits, the Fund said. That is where it sees possible weak links. Customer contracts often back the loans, so a broken offtake agreement can tighten the credit as well as the equity.
Investors have added their own gearing on top. Hedge funds’ gross equity positions plus margin loans have grown since 2024 and now equal about 15 percent of advanced economies’ GDP, up from 10 percent. Retail money has followed through geared exchange-traded funds, which magnify daily moves. Single stocks now make up 28 percent of those funds, up from 16 percent, a concentrated bet on the same AI names the circular deals already tie together.
Which Markets Would an AI Selloff Hit First?
Athanasios Vamvakidis, deputy director in the Monetary and Capital Markets Department, told the Bangkok briefing that an AI market correction will affect the real economy. He said global risk appetite had been strong, backed by earnings and optimism about AI, and then drew the line the report is built on: resilience is not necessarily safety. The Fund’s own phrase in the report is blunt. “The consequences of an AI correction could be global.”
WHERE AN AI CORRECTION WOULD LAND FIRST
- Advanced Asia: Stock markets there move most closely with global AI shares and would likely take the largest direct hit, the Fund said.
- Hardware exporters: South Korea, Malaysia, Mexico, and Thailand were among the names lifted in the growth upgrade because they supply AI kit; a spend cut would reverse that channel.
- Europe through Wall Street: Euro-area and UK prices are less sensitive to AI shares, but stress can still arrive through much larger holdings of US equities.
- Geared funds and prime brokers: Forced selling from margin loans and geared ETFs can raise equity volatility even if the first miss is at one weaker borrower.
- Neocloud credit: Debt tied to a handful of offtake contracts can reprice when a customer’s revenue promise is marked down.
The growth paper already shows how narrow the boom has become. Just 32 economies now account for 95 percent of global growth, down from 54 in the April outlook. A shock that starts in a few US platforms and a few Asian suppliers does not need a broad recession to travel.
Equity, Debt and Revenue Promises Can Fail Together
Wu walked reporters through why the staff treats these contracts as more than ordinary vendor finance. The unusual piece, he said, is the future revenue commitment that closes the loop. If questions arise about whether AI spending will pay, three hits can arrive together.
If there are questions about the monetization in AI, the equity investments will deplete in value. The debt may be difficult to service and the revenue commitments in the future may not materialize.
Jason Wu, assistant director, IMF Monetary and Capital Markets Department, press briefing in Bangkok
He called that a triple whammy. He also said the mapping of the 14 deals shows certain companies and nodes are particularly exposed, so trouble at those entities would feed back through the rest of the circle. In the staff technical note, Chen, Gautam, and Wu wrote that the cycle is still anchored by highly profitable incumbents with strong balance sheets, but that investment is becoming more capital intensive and more dependent on outside finance. Technological obsolescence, high market concentration, and rising co-movement among AI-related firms could then amplify a miss if monetization or productivity gains disappoint.
That is the design risk, not a forecast that the models fail. The money is real, it is increasingly borrowed, and it is pointed at a short list of counterparties who have promised to buy from one another for years.
Banks Stay Upright, With 22% of Assets in the Weak Tail
The 2026 bank stress test folded the AI scenario into a wider shock that also included an energy-price spike and higher inflation and bond yields. The global banking system would remain broadly resilient, the Fund said. The weak tail is longer than it was a year ago.
WHAT THE 2026 STRESS MAP MOVED
- Weak-bank share: Banks holding 22% of global banking assets would end the test with core capital ratios below 7 percent, up from 18 percent a year earlier.
- Hedge-fund scale: The industry now holds about $13 trillion in assets, more than three times its 2013 level, with few limits on strategy or borrowing.
- Nonbank pressure: Insurers and pension funds hold more assets that are hard to sell quickly; private credit faces higher borrower leverage and liquidity strain.
- Policy ask: Authorities should contain excessive borrowing behind AI bets, including limits on margin loans, geared exchange-traded products, and derivatives.
Vamvakidis said unresolved vulnerabilities could amplify shocks, and that a tail of weak banks in this scenario would be undercapitalized, a share that has been increasing. Several of those banks have heavier ties to nonbank lenders, which is how an equity-market miss can show up in credit even when the largest lenders still clear the test.
Software Makers Get Almost No Time to Patch
The third shock in the report is cyber, and the Fund ties it to the same AI tools that are supporting growth. State-sponsored groups, ransomware gangs, and insiders now have access to frontier models that have shown strong results in network-attack simulations. In June, Georgieva warned that Mythos-class models could be turned against the financial system.
Attackers are also moving faster than the people who write the patches. In more than 70% of cases this year, software providers had almost no time to fix a flaw before it was exploited, 20 percentage points more than a year earlier. In 2021, providers typically had close to 300 days. Those two readings are different clocks: one is the share of incidents with almost no window, the other is how long a typical window used to last.
Severe incidents, the Fund said, could undermine market confidence and disrupt payments, trading, or access to deposits. Vamvakidis told reporters that the risks are both known and very much unknown, and that the policy priority should be to strengthen resilience before new shocks hit. The report’s other ask sits next to that one: put public debt on a sustainable path, because a spike in sovereign yields is the remaining trigger on the same list.
The two Bangkok papers can both be right at once. AI capital is holding 2026 growth near 3.1 percent, and the way that capital is being raised, lent, and promised back as future sales is one of the triple whammy channels that could tighten conditions if the orders slip. The Fund asked governments to limit the extra borrowing around those bets and to harden cyber defenses while the meetings in Bangkok continue.
Frequently Asked Questions
What Are Circular AI Deals?
They are contracts in which a stronger AI firm invests equity or arranges debt for a weaker one and, in the same relationship, books future chip or cloud orders from that firm. Wu told the briefing that the $650 billion debt total includes off-balance-sheet vehicles, and that the future revenue commitments are what make the structure unusual next to older supplier-finance deals.
Did the IMF Change Its 2027 Growth Forecast Too?
No. The October World Economic Outlook held 2027 global growth at 3.4 percent, unchanged from July and 0.2 percentage point higher than the April figure. The 0.1 point upgrade applies only to 2026.
What Inflation Path Did the October Outlook Publish?
Global headline inflation is projected to rise to 4.7 percent in 2026, then ease to 4.1 percent in 2027. The Fund linked the increase to higher energy costs and the AI investment boom, and it said energy importers outside the technology chain face the hardest mix of those prices and weaker demand.
Did IMF Staff Call Circular AI Financing a Crisis Already?
No. The October 9 technical note by Chen, Gautam, and Wu says current financial stability risks appear manageable, while warning that vulnerabilities could build as leverage, concentration, and interconnectedness increase. The stability report treats a correction as a plausible near-term catalyst, not as an event that has begun.
How Large Are Hedge Funds in the Same Stability Report?
Chapter 2 of the October report says hedge funds now hold about $13 trillion in assets, more than three times their 2013 level. The chapter finds they can support liquidity in calm markets and, in stress, can deleverage together through crowded trades and redemptions, with spillovers onto prime brokers.
Disclaimer: This article is news reporting and analysis of IMF publications and related public remarks, and it is for information only. It is not investment advice, a recommendation to buy or sell any security, bond, fund, or derivative, and it is not a forecast that an AI-related correction will or will not occur. Readers should consult a licensed financial adviser or investment professional about their own holdings and risk limits before making any decision. Figures, stress-test outcomes, and forecasts reflect the IMF reports and other named sources as of the dates given in the piece and can change with later data, ratings, or policy.

Kering’s Growing Houses Cannot Outrun a Shrinking Gucci

Studio Staff and Bitcoin Buyers Built the Eminem Leak Case

A Mutated H1N1 Strain Is Hitting Younger Immunity First

Albert Heijn Returns at One-Third as Rivals Take Share

Art Basel Paris Ends After One Public Day

Thameslink Will Pad 60,000 Ironing-Board Seats From 2027

How Tall Was Adolf Hitler Really? Debunking the Myth of his Height

Micron Sells the Memory Shortage as Five-Year Contracts

Royal Caribbean Sends Los Angeles Ships to Singapore and Brisbane

U.S. Forces Clear Hormuz Mines, Then Hit Minelayers Again
-
 NEWS2 months ago
Thameslink Will Pad 60,000 Ironing-Board Seats From 2027
-
 SCIENCE3 years ago
How Tall Was Adolf Hitler Really? Debunking the Myth of his Height
-
 NEWS2 months ago
Micron Sells the Memory Shortage as Five-Year Contracts
-
 NEWS2 months ago
Royal Caribbean Sends Los Angeles Ships to Singapore and Brisbane
-
 BUSINESS2 months ago
U.S. Forces Clear Hormuz Mines, Then Hit Minelayers Again
-
 BUSINESS2 months ago
Sweetmore Bakeries Buys Fantasy Baking for Bar Work
-
 BUSINESS2 months ago
L Catterton Installs a Kraft Heinz Operator at Kettle Cuisine
-
 NEWS2 months ago
CISA’s 100 Water System Hacks Hit One-Operator Plants